
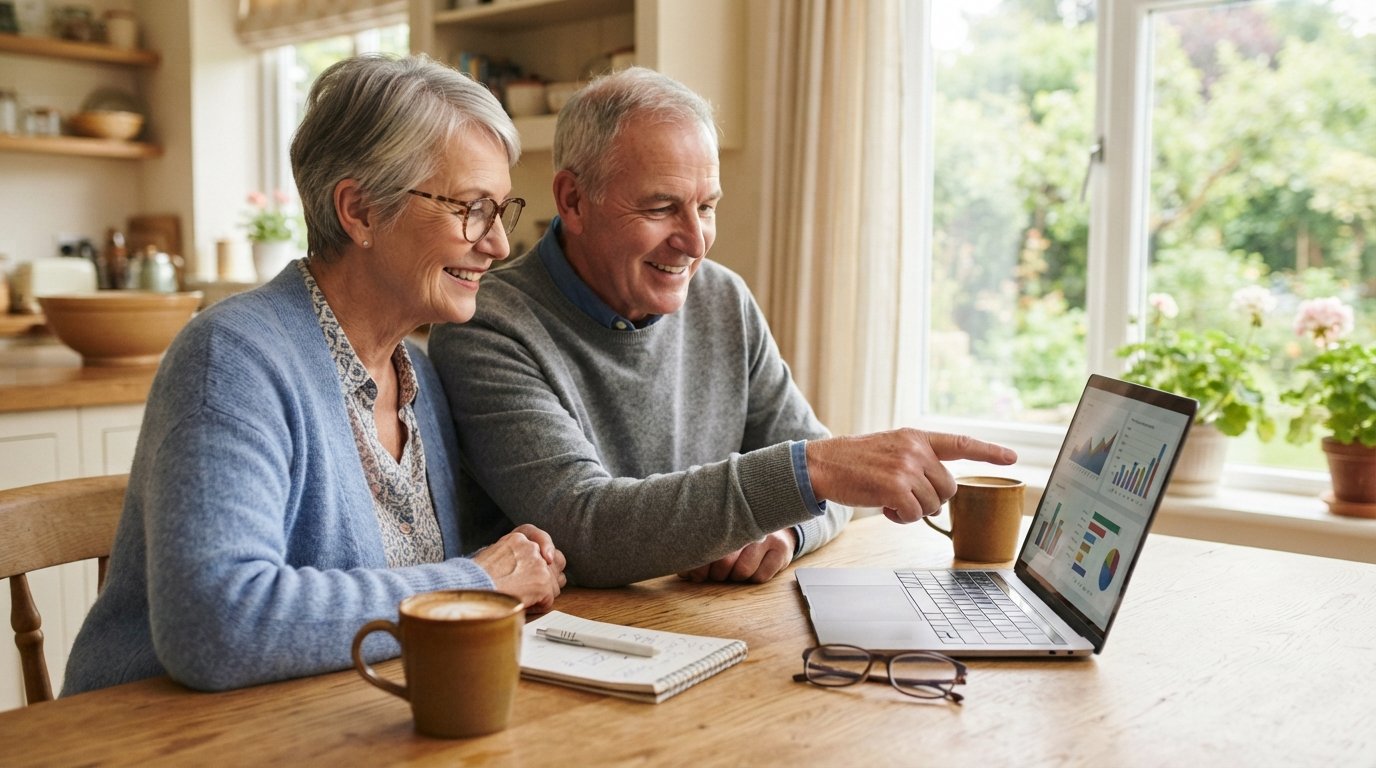
How to Compare Life Insurance Quotes Online for Seniors
Compare life insurance quotes online for seniors with our step-by-step guide. Call (833)-212-4240 to get personalized help and lower your premium today.
By Amelia Ellis
Finding affordable life insurance as a senior does not have to be a frustrating maze of phone calls and pushy sales pitches. With the right approach, you can sit at your kitchen table, request multiple personalized quotes in minutes, and make a confident decision without ever feeling pressured. The key is knowing exactly what information you need, how to evaluate offers beyond the monthly price, and which warning signs signal that a quote is not worth your time. This guide walks you through the entire process of comparing life insurance quotes online for seniors, step by step, so you can protect your family without overpaying.
What Information You Need Before Requesting Quotes
Accurate quotes depend on accurate inputs. Most online quote platforms, including LifeAgency.com, ask for three core pieces of information: your ZIP code, your age, and whether you use tobacco. These details allow the system to match you with participating insurers that operate in your state and price policies according to your risk profile. Providing correct information from the start prevents surprises later when you apply for coverage.
Beyond those basics, some quote forms may ask about your height and weight, existing health conditions, or the coverage amount you have in mind. Seniors often qualify for simplified issue or final expense policies that do not require a medical exam, but the available options vary by insurer. Having a rough idea of how much coverage you need, typically between $10,000 and $300,000 for seniors aged 50 to 74, helps you compare apples to apples. If you are unsure about the right amount, a licensed agent can help you estimate based on final expenses, outstanding debts, and the support you want to leave behind.
Gather your documents and details before you start. You will need your date of birth, Social Security number for formal applications (though not for initial quotes), and a list of any prescription medications you take. This preparation saves time and ensures the quotes you receive are realistic. Remember that quote platforms are not insurance agencies themselves; they connect you with licensed professionals who can finalize your policy.
Why Comparing Multiple Offers Can Lower Your Premiums
Insurance companies price risk differently. One insurer may view a 68 year old with controlled hypertension as a standard risk, while another may offer a preferred rate. If you only request one quote, you have no way of knowing whether you are getting a competitive deal. Comparing multiple offers side by side is the single most effective way to reduce your premium without sacrificing coverage.
Studies consistently show that seniors who compare at least three quotes save significantly compared to those who accept the first offer. The savings can range from a few dollars to several hundred dollars per year, depending on your health profile and the type of policy. For example, a final expense policy with a $15,000 death benefit might cost $45 per month with one carrier and $62 per month with another, even though the benefits are identical. Over a decade, that difference adds up to thousands of dollars.
Comparing quotes also reveals which insurers are senior friendly. Some companies specialize in no medical exam policies for older applicants, while others penalize any health history. By requesting quotes from several sources, you naturally filter out the carriers that are not competitive for your situation. The process takes only a few minutes per quote, and the financial payoff is well worth the effort.
Step by Step How to Compare Life Insurance Quotes Online for Seniors
Follow this sequence to streamline your comparison and avoid common pitfalls. Each step builds on the previous one, ensuring you gather the right information and evaluate it fairly.
- Determine your coverage goal. Decide whether you need term life, final expense, or a no medical exam policy. Seniors often choose final expense coverage to handle burial costs and small debts, while those with dependents may need a larger term policy.
- Use a reputable quote platform. Enter your ZIP code, age, and tobacco status on a site that connects you with multiple licensed insurers. Avoid sites that demand your phone number before showing any results.
- Request at least three quotes. Compare premiums, death benefits, and policy terms. Do not stop at the first low number; verify what is included.
- Review the insurer's rating and reputation. Check AM Best or similar ratings for financial strength. Read customer reviews for claims handling and service quality.
- Speak with a licensed agent if needed. Ask clarifying questions about exclusions, waiting periods, and premium increases. A good agent will not pressure you and will explain the fine print.
After completing these steps, you will have a shortlist of two or three policies that meet your needs. Take your time reviewing them. The goal is not just the lowest premium but the best overall value for your family. If you are married, consider how a joint policy or two separate policies might serve you better; our article on protecting your family with life insurance after marriage offers useful guidance on coordinating coverage with a spouse.
Red Flags to Avoid When Comparing Online Quotes
Not every quote you encounter online is legitimate or transparent. Seniors are frequent targets for aggressive marketing, so knowing the warning signs protects your wallet and your personal information. Watch for these red flags before you share any sensitive data.
- Requests for payment upfront. Legitimate quote platforms do not charge you to see quotes. If a site asks for a credit card before showing results, walk away.
- Guaranteed acceptance with no health questions. While no medical exam policies exist, they still ask health questions. A promise of guaranteed approval regardless of health is often a bait and switch.
- Pressure to buy immediately. High pressure sales tactics, such as limited time discounts or threats that the rate will disappear, are signs of a pushy agent or a scam.
- Missing insurer names. A quote that does not disclose which insurance company is backing the policy is worthless. You need to know the carrier to verify its ratings.
- Unusually low premiums that seem too good to be true. Compare the death benefit and policy terms; sometimes the low price reflects a much smaller benefit or a long waiting period.
If you encounter any of these red flags, move on to a different platform. Reputable comparison services, like the one at LifeInsurance-Quote.com, connect you with licensed agents who analyze your needs and suggest affordable plans without pressure. They understand that seniors deserve clear, honest information to make informed decisions.
Evaluating Insurers and Policy Details Beyond Price
Price is important, but it is not the only factor. A low premium from a financially unstable insurer could leave your family without a payout when they need it most. When comparing quotes, examine the insurer's financial strength ratings from AM Best, S&P, or Moody's. Ratings of A or better indicate a strong ability to pay claims. Also check the company's complaint ratio with your state insurance department; a high volume of complaints about claims denials is a serious concern.
Policy details matter just as much as the insurer's reputation. Look closely at the death benefit, which is the amount your beneficiaries receive. Confirm whether the premium is guaranteed never to increase and whether the policy builds cash value (whole life) or is pure protection (term life). For final expense policies, understand the waiting period: many simplified issue policies have a two year graded benefit, meaning full coverage applies only after two years. If you need immediate coverage, look for policies with no waiting period, even if the premium is slightly higher.
Read the exclusions carefully. Common exclusions include death by suicide within the first two years and misrepresentation on the application. Seniors with health issues should pay special attention to how the insurer handles pre existing conditions. Some policies offer accelerated death benefits for terminal illness, which can be valuable if you face a serious diagnosis. Finally, consider the application process: no medical exam policies often require only a phone interview and a prescription check, making them faster and less invasive for seniors.
Making Your Final Decision with Confidence
Once you have compared quotes and evaluated the details, you are ready to choose a policy. Do not rush this step. Review your shortlist with a family member or trusted advisor if possible. Confirm the premium payment schedule (monthly, quarterly, annually) and set up automatic payments to avoid lapses. Keep copies of your policy documents in a safe place and inform your beneficiaries about the coverage.
Remember that you are not alone in this process. Licensed agents can answer questions and guide you through the application without any obligation to purchase. If you are unsure which policy fits your budget, ask for a side by side comparison of the top two options. The right policy is one that provides peace of mind without straining your finances. By following the steps outlined here, you have mastered how to compare life insurance quotes online for seniors and can move forward with confidence. For personalized assistance, call (833)-212-4240 to speak with a licensed professional who can help you finalize your choice.