
Life Insurance for Seniors with High Blood Pressure
Find life insurance for seniors with high blood pressure. Compare no-exam options and get the best rate. Call (833)-212-4240 for expert help.
By Olivia Lawson
If you are a senior managing high blood pressure, you may assume that life insurance is out of reach or that any policy you find will come with a prohibitively high price tag. The reality is far more encouraging. Millions of older adults live with hypertension, and the insurance industry has adapted to serve them. In fact, having high blood pressure does not automatically disqualify you from coverage. What matters most is how well your condition is managed, what your recent readings show, and which type of policy you apply for. With the right preparation and a clear understanding of how underwriting works, you can secure a policy that protects your family without straining your budget.
This guide walks you through the key factors insurers evaluate when you have hypertension, the types of policies that are most accessible, and practical steps you can take to present your health history in the best possible light. Whether your blood pressure is well controlled or has been difficult to manage, you have options. The goal is to help you compare life insurance for seniors with high blood pressure confidently and find a plan that fits your needs.
How High Blood Pressure Affects Life Insurance Underwriting
When you apply for life insurance, the insurer assesses your risk of mortality. High blood pressure, also called hypertension, is a common condition that, if left uncontrolled, can lead to heart disease, stroke, and other serious health issues. Insurers therefore look closely at your blood pressure history to determine how much risk you present. However, a diagnosis alone does not tell the whole story. Underwriters focus on the severity of your condition, your treatment plan, and whether your readings fall within acceptable ranges.
The distinction between controlled and uncontrolled hypertension is the single most important factor in underwriting. If your blood pressure is well managed through medication, lifestyle changes, or both, and your readings consistently stay near normal, you are likely to qualify for better rates. On the other hand, if your blood pressure remains elevated despite treatment, or if you have other health complications, insurers may view you as a higher risk. This does not mean you will be denied, but it may affect the type of policy you can get and the premium you pay.
Insurers typically request a medical exam or a paramedical visit for traditional fully underwritten policies. During this exam, a professional records your blood pressure and may take blood and urine samples. They also review your medical records, including your history of readings and medications. For seniors with high blood pressure, this information helps the insurer place you in a risk class. Preferred classes are reserved for those with excellent health and well-controlled numbers, while standard or substandard classes may apply to those with more elevated readings or additional risk factors. Understanding where you fall can help you set realistic expectations and choose the right application path.
No Medical Exam Options for Seniors with Hypertension
For many seniors, the idea of a medical exam can be a barrier. It may be inconvenient, time-consuming, or stressful. Fortunately, there are life insurance policies that do not require a medical exam, and these can be particularly valuable for people with high blood pressure. Simplified issue policies rely on a questionnaire about your health and lifestyle rather than a physical exam. Final expense insurance, also known as burial insurance, is another popular option that often features simplified underwriting. These policies typically offer smaller coverage amounts, such as $10,000 to $50,000, and are designed to cover funeral costs and other end-of-life expenses.
Simplified issue policies are not automatically available to everyone with hypertension. Insurers still ask detailed questions about your condition, including your diagnosis date, medications, and recent readings. Some simplified issue policies may accept you even if your blood pressure is not perfectly controlled, but they may charge a higher premium or limit the death benefit during the first few years. Guaranteed issue policies are the most lenient, accepting applicants regardless of health, but they come with a waiting period (often two years) before full benefits apply and have higher costs per thousand dollars of coverage. For seniors with high blood pressure, simplified issue is often the sweet spot between accessibility and affordability.
When you apply for a no medical exam policy, honesty is critical. The application will ask specific questions, such as whether you have been hospitalized for hypertension, whether you have had a heart attack or stroke, and whether you take medication. Answer truthfully. If you omit information or misrepresent your health, the insurer could deny a claim later. If you are unsure about which no-exam options fit your situation, our guide on no medical exam life insurance for seniors over 80 provides additional context that may be helpful, even if you are younger.
Medications and Readings That Impact Eligibility
Insurers look at the medications you take to manage high blood pressure. Common medications such as ACE inhibitors, beta-blockers, calcium channel blockers, and diuretics are generally viewed favorably because they indicate that your condition is being treated. However, the number of medications and the dosages can influence your risk classification. If you take multiple medications or have recently had your dosage adjusted, the insurer may want to see a history of stable readings. They may also check for medication compliance by reviewing your pharmacy records or asking you directly.
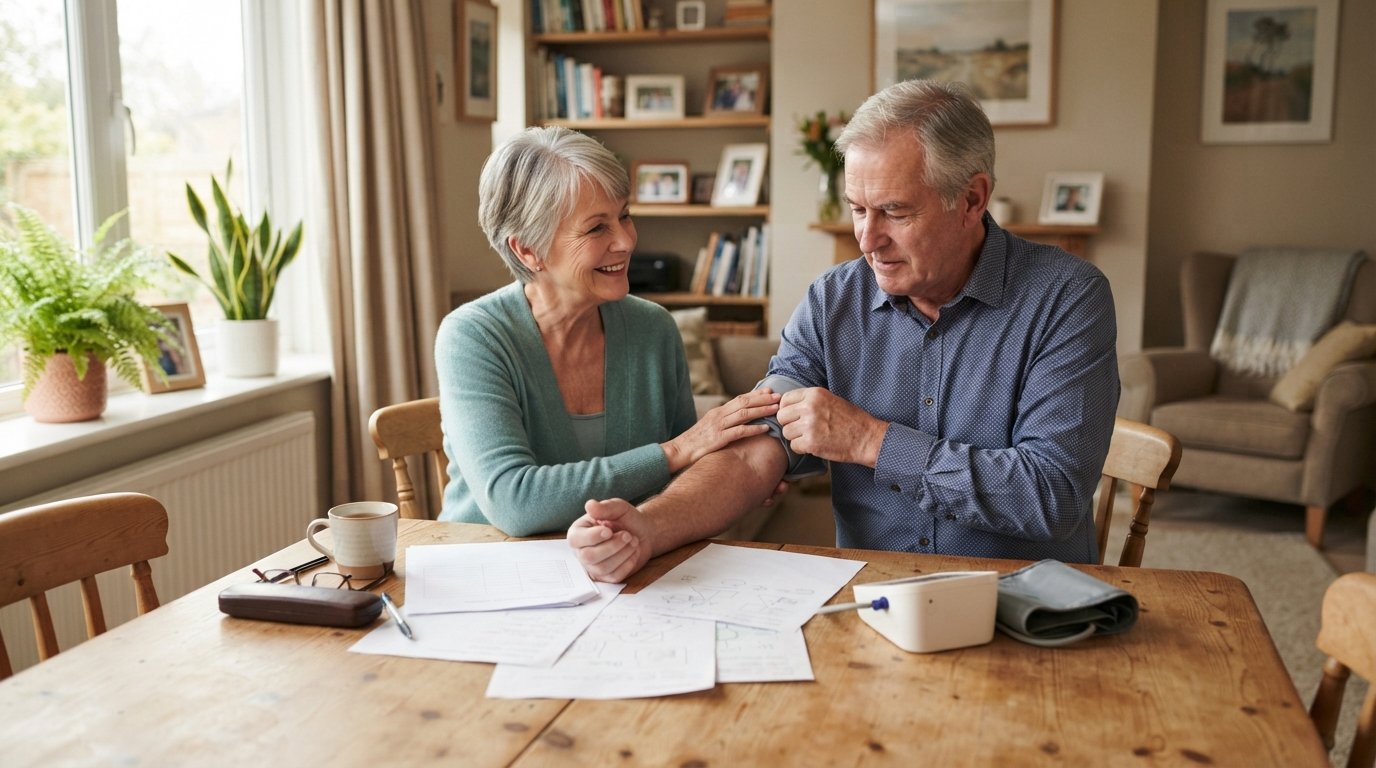
Your blood pressure readings are equally important. Insurers typically want to see readings below 140/90 mmHg, and the best rates are often available for those with readings below 130/80 mmHg. If your readings are consistently higher, you may still qualify for coverage, but you might be placed in a higher risk class. It is helpful to bring a log of recent readings from home monitoring to your application or exam. This shows the insurer that you are actively managing your health and provides a more complete picture than a single reading taken at the exam. Keep in mind that a one-time elevated reading due to nerves (white coat syndrome) is common, and insurers may take that into account.
Other health factors can compound the risk associated with hypertension. For example, if you have diabetes, high cholesterol, or a history of smoking, the insurer will consider how these conditions interact with your blood pressure. Maintaining a healthy weight, exercising regularly, and following a balanced diet can improve your readings and your overall risk profile. Before applying, consider making small lifestyle changes and documenting them. Even modest improvements can positively impact your underwriting outcome.
Tips for Comparing Quotes with a Hypertension History
Comparing quotes from multiple insurers is essential, especially when you have a pre-existing condition like high blood pressure. Different insurance companies have different underwriting guidelines. One insurer might specialize in seniors with manageable hypertension and offer competitive rates, while another might be more conservative. Working with a platform that connects you to multiple carriers can save you time and help you find the best deal. LifeInsurance-Quote.com is one resource where you can request personalized quotes from licensed agents who understand the nuances of hypertension underwriting.
When you request quotes, be prepared to provide accurate information about your health. This includes your most recent blood pressure readings, a list of your medications, and any other health conditions you have. The more transparent you are, the more accurate your quotes will be. It is also wise to ask about the underwriting process: some policies may be approved instantly, while others may require a phone interview or a review of medical records. Understanding the timeline can help you plan accordingly.
Here are a few practical steps to streamline your comparison:
- Gather your health information. Collect recent blood pressure readings, a list of medications and dosages, and dates of any hypertension-related medical visits. This will speed up the application process.
- Decide on coverage amount and term. Determine how much coverage you need and whether you prefer term or permanent insurance. Final expense policies are often permanent and easier to qualify for.
- Work with an independent agent or comparison platform. An agent who represents multiple carriers can match you with companies that are friendly to applicants with hypertension.
- Review the fine print. Check for waiting periods, graded death benefits, and any exclusions related to pre-existing conditions. Understand what you are buying before you sign.
- Consider a hybrid approach. If you are not ready to commit, you can start with a smaller simplified issue policy and later add more coverage if your health improves.
After you receive quotes, compare not just the premium but also the insurer's reputation, financial strength, and customer service. A slightly higher premium from a highly rated company may be worth it for peace of mind. Also, ask about the application process: some no-exam policies can be approved within days, while others may take weeks. If you need coverage quickly, prioritize insurers with fast turnaround times.
Frequently Asked Questions About Life Insurance and Hypertension
Seniors often have specific questions about how their blood pressure will be viewed. One common concern is whether they will be denied outright. The answer is no: most applicants with hypertension are approved, though the rate class may vary. Another question is whether they need to wait until their blood pressure is perfect before applying. In most cases, waiting is not necessary, but improving your numbers can lead to better rates. It is also worth noting that if you have had a recent change in medication, the insurer may want to see a period of stability before offering preferred rates.
Some people wonder if they can get coverage without a medical exam if their blood pressure is severe. Simplified issue policies may still be available, but the questionnaire will dig deeper. If you have a history of hypertensive crisis or hospitalization, you may need to consider guaranteed issue policies. These are more expensive and have waiting periods, but they guarantee acceptance. A licensed agent can help you navigate these options and choose the one that aligns with your health profile and budget.
Finally, remember that life insurance is not just about the death benefit. It is about protecting your loved ones from financial burden. Whether you choose a small final expense policy or a larger term policy, having coverage in place can provide invaluable peace of mind. Take the time to explore your options, ask questions, and compare quotes. With the right approach, you can find life insurance for seniors with high blood pressure that fits your needs and your wallet.
Start by requesting a quote from a trusted comparison service. Have your health details ready, and don't be afraid to ask for help. The process is more accessible than you might think, and the protection you secure today can benefit your family for years to come.