
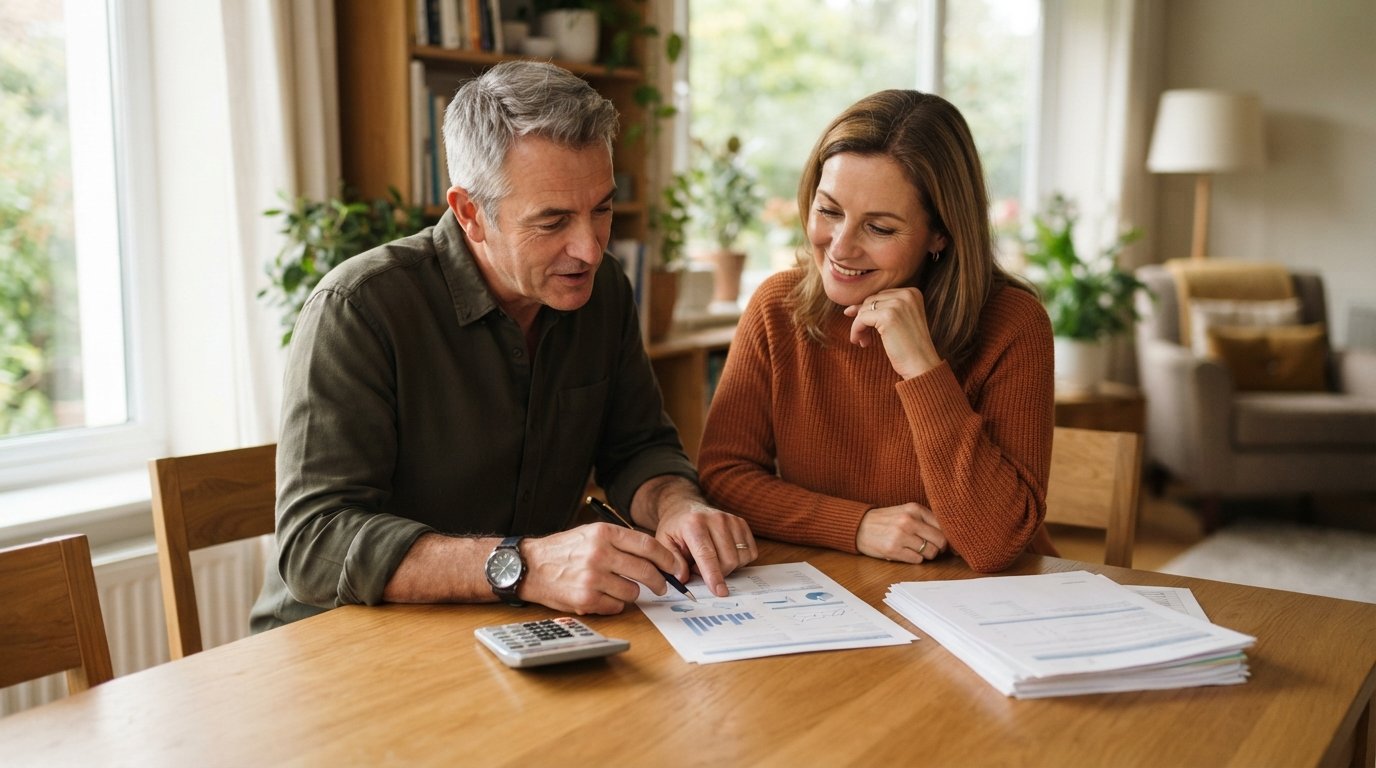
What Coverage Amount Should I Carry Life Insurance?
Determine the right life insurance coverage amount for your needs. Call (833)-212-4240 for personalized guidance and peace of mind.
By Caleb Foster
Choosing a life insurance coverage amount can feel like guessing at a number that will either leave your family short or cost you more than necessary. The truth is, there is no single magic figure that works for everyone. The right amount depends on your income, debts, future obligations, and the people who rely on you. But you do not need to be an actuary to get it right. With a few clear guidelines and some basic math, you can land on a coverage amount that protects your family without overpaying. This article walks you through the factors that matter most, how your needs shift over time, and how to use simple tools to narrow your range. If you are asking, "what coverage amount should I carry life insurance?" you are already on the right track. Let us turn that question into a confident answer.
Start With Your Financial Obligations
Every coverage calculation begins with the same foundation: what would your family need to pay for if you were no longer there? The answer usually falls into three broad buckets: replacing your income, clearing debts, and covering final expenses. Most people underestimate the first bucket and forget the third entirely. Taking stock of each category gives you a realistic starting point.
Income replacement is typically the largest piece. If your family relies on your paycheck to cover rent, groceries, utilities, and everyday living, that income stream needs to continue. A common rule of thumb is to multiply your annual income by 10, but that is just a starting point. If you earn $60,000 a year, a $600,000 policy would replace a decade of income. That sounds like a lot, but consider that your family might need that money to last longer than ten years if they also have a mortgage or college costs ahead.
Next, list your debts. This includes your mortgage balance, car loans, student loans, credit card balances, and any personal loans. Add them up. If you carry a $300,000 mortgage and $20,000 in other debt, your policy should cover at least $320,000 just to clear the slate. Final expenses are the third bucket. Funerals and burial costs often run between $8,000 and $15,000, and there may be medical bills or estate settlement costs on top of that. Even a modest final expense buffer keeps your family from scrambling during an already difficult time.
When you combine these three buckets, you get a baseline number. For many people, that baseline lands somewhere between $250,000 and $750,000. If you are a stay-at-home parent, your income replacement figure may be lower, but do not overlook the value of unpaid services like childcare, transportation, and household management. Replacing those services could cost tens of thousands of dollars per year.
How Age and Life Stage Change Your Coverage Needs
Your coverage needs are not static. They shift as your mortgage balance falls, your children grow up, and your savings grow. A 30-year-old with a new mortgage and two young children typically needs far more coverage than a 60-year-old whose kids are independent and whose home is nearly paid off. Understanding where you are in that arc helps you avoid buying too little when your obligations peak or too much when they have shrunk.
In your 20s and 30s, you are often in the accumulation phase: new career, new family, new debts. This is when coverage needs are highest. A 30-year-old earning $50,000 with a $250,000 mortgage and a child on the way might need $500,000 to $750,000 to replace income for 15 to 20 years and clear the mortgage. In your 40s and 50s, your income may have grown, but your mortgage is smaller and your retirement savings are larger. You might still need substantial coverage, but the duration matters more than the amount. A 20-year term policy could carry you until your youngest child graduates and your home is paid off.
By your 60s and beyond, the picture changes again. If you are retired or close to it, income replacement is less critical, but final expenses and outstanding debts remain. Many people in this stage shift to smaller policies, such as $10,000 to $50,000, to cover funeral costs and leave a modest legacy. If you are married, you may also want to consider coverage for your spouse. For a deeper look at how marriage changes your coverage priorities, see our guide on protecting your family with life insurance after marriage.
One practical way to track your needs is to reassess every few years or after major life events: a new child, a new home, a promotion, or a divorce. Each of these changes your obligations and, by extension, your ideal coverage amount.
Common Coverage Amounts and What They Can Cover
While your exact number will be personal, seeing how common coverage amounts break down can help you sanity-check your target. The ranges below reflect what different policy sizes can typically cover, but remember that costs vary by age, health, and term length.
- $10,000 to $50,000: Best for final expenses, small debts, and a modest legacy. Often used by seniors or people with limited obligations.
- $100,000 to $250,000: Covers a small mortgage, some income replacement, and final expenses for a family with modest needs.
- $250,000 to $500,000: A common range for parents with a mortgage and children at home. Covers several years of income plus debt.
- $500,000 to $1,000,000: Suitable for higher earners or families with large mortgages, college savings goals, or significant debt.
These ranges are not rules, but they are useful benchmarks. If your calculation lands at $400,000, you are in good company. If it lands at $800,000 because you have a large mortgage and three kids, that is equally valid. The key is to match the policy to your actual obligations, not to a generic average.
One caveat: if you are over 50 and looking for coverage without a medical exam, the maximum available amount may be lower. Many no-medical-exam policies cap at $250,000 or $300,000, and some final expense policies offer $10,000 to $50,000. If your needs exceed those caps, you may need to combine a smaller no-exam policy with a term policy or consider a fully underwritten option. A licensed agent can help you compare what is available in your age band.
Using Calculators and Quote Tools to Narrow Your Range
Once you have a rough target, online calculators and quote tools can help you refine it. Most life insurance calculators ask for your income, debts, savings, and number of dependents. They then apply a formula to estimate a coverage range. These tools are not perfect, but they are fast and can catch gaps in your thinking. Run two or three different calculators and see where they cluster. If one says $300,000 and another says $600,000, that spread tells you to dig into the assumptions behind each.
After you have a range, the next step is to see what that coverage actually costs. This is where quote comparison tools shine. You can enter your ZIP code, age, and tobacco use to see personalized quotes from multiple carriers. Comparing quotes side by side helps you see whether a $500,000 policy is affordable or whether a $350,000 policy with a longer term makes more sense for your budget. It also reveals how much rates vary between carriers for the same coverage, which can be thousands of dollars over the life of the policy.
At LifeAgency.com, you can request personalized quotes without any signup or obligation. The platform connects you with licensed insurance agents who can help you interpret the numbers and choose a plan that fits your needs and budget. You can also visit LifeInsurance-Quote.com to explore additional quote options and see how different coverage amounts affect your premium. The goal is not to buy the biggest policy, but the right one.
As you compare, keep these practical tips in mind:
- Decide on a term length first. A 20-year term often aligns with the years your children are dependent and your mortgage is outstanding. A 30-year term may be better if you have young children or a long mortgage.
- Round up slightly. If your calculation lands at $420,000, consider $450,000 or $500,000. The premium difference is often small, and the extra cushion covers inflation and unexpected costs.
- Do not ignore your spouse. If you are married, calculate coverage for both partners, even if one stays at home. The surviving spouse may need to pay for childcare or other services that were previously unpaid.
- Review your policy every few years. As your debts fall and your savings grow, you may be able to reduce coverage or adjust your term. Conversely, a new child or a new mortgage may call for an increase.
One final consideration: do not let the perfect number paralyze you. It is better to carry a reasonable amount of coverage now than to delay and leave your family unprotected. You can always adjust later. The most important step is to start with a clear-eyed look at your obligations and use the tools available to turn that look into a concrete plan.
Whether you are just starting to explore life insurance or you are revisiting an existing policy, the question of how much coverage to carry is one of the most important financial decisions you will make. By focusing on your income replacement needs, debts, and final expenses, and by using calculators and quote tools to compare options, you can arrive at a number that protects your family without straining your budget. Take the time to run the numbers, compare quotes, and speak with a licensed agent if you need guidance. Your future self, and your family, will thank you.